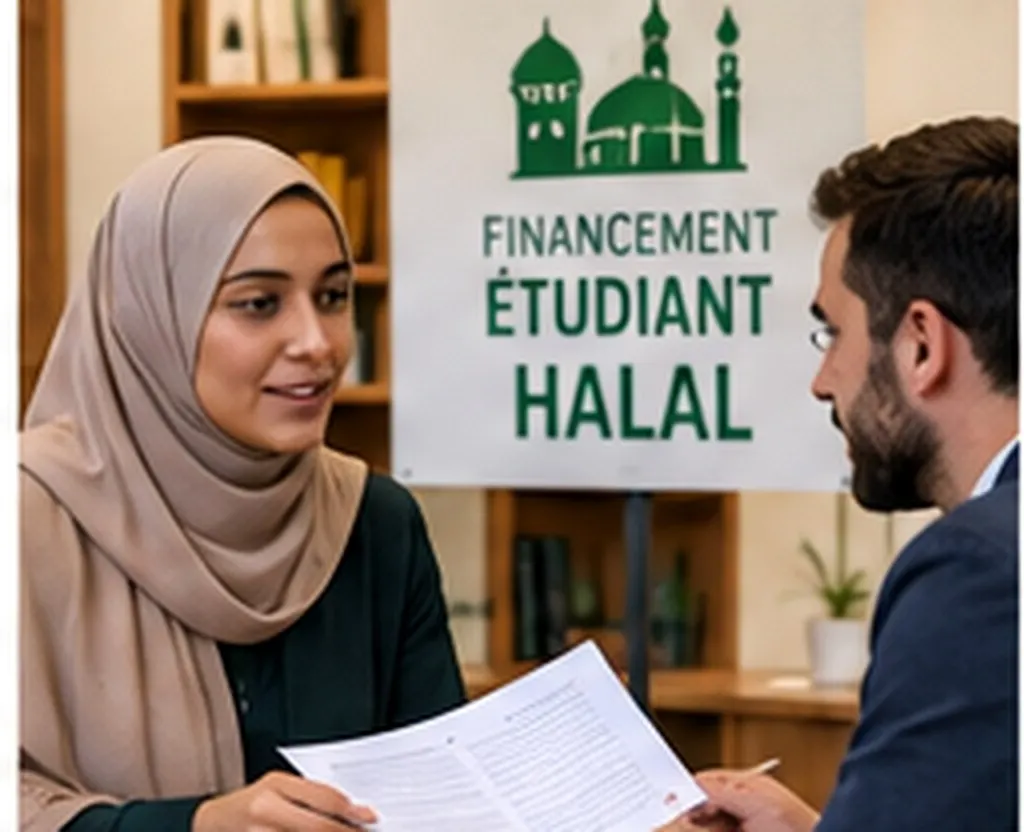
Why many Muslim students look for halal student finance
Halal Student Finance describes ways of paying for a degree that respect Islamic commercial ethics, above all the prohibition of riba, instead of relying on the interest-bearing loans that most systems offer. Islamic commercial ethics prohibit riba, usually translated as interest: a lender may not earn a predetermined return simply for lending money. For a student this creates a real dilemma, because the default way of financing a degree in most countries is an interest-bearing loan, whether it comes from a government agency or a bank. Halal student finance covers the products and strategies that let you pay for education while respecting that principle, from interest-free benevolent loans to sale and lease structures approved by a Sharia supervisory board.
Scholars do not all reach the same conclusions on every product, and a structure accepted by one board may be criticised by another. Here is how the main options work financially; for the religious assessment, ask a qualified scholar you trust and read the fatwa or certificate issued for the specific product.
The main Islamic structures used to fund studies
Qard hasan: the benevolent loan
A qard hasan is a loan repaid at its face value, with no profit for the lender. It is the cleanest structure from a Sharia perspective, and it is what many mosques, community funds, zakat committees and Muslim charities offer to students. A modest administrative fee that reflects actual costs is generally considered acceptable; a fee that rises with the amount or the duration is not.
Murabaha: cost-plus sale
The financier buys an asset (a laptop, equipment, sometimes a course place where the school allows it) and sells it to you at a disclosed mark-up, payable in instalments. The profit is fixed at the outset and does not grow if you pay late, although late payment charges are often directed to charity.
Ijara and service-based contracts
In an ijara the financier leases an asset or a service to you for rent. Variants based on a service fee (ujrah) are used in some national schemes: Malaysia's public higher education fund PTPTN, for example, moved its loans to an ujrah-based charge to make them acceptable to Muslim borrowers.
Tawarruq: the contested option
Tawarruq, or commodity murabaha, involves buying a commodity on credit and selling it immediately for cash. Many banks use it, but a number of scholars and the fiqh academy of the OIC have criticised organised tawarruq as interest in all but name. Check carefully before relying on it.
Takaful-based models
A takaful fund pools contributions from participants and pays out on agreed terms. The UK government designed its proposed Alternative Student Finance around this idea, with graduates contributing to a common fund rather than paying interest.
Halal student finance country by country
United Kingdom
Standard Student Finance England, Wales, Scotland and Northern Ireland loans carry interest, though repayments are linked to income. A Sharia-compliant Alternative Student Finance product has been promised for several years; check its current status and start date directly with Student Finance England before planning around it. A few UK Islamic banks offer personal finance on murabaha terms, which can cover specific costs.
France and Belgium
There is no Islamic version of the French State-guaranteed student loan. The most practical interest-free routes are means-tested CROUS grants, regional and university aid, and the interest-free student honour loan offered by associations and foundations. Some students also use zero-interest family loans formalised in writing.
Germany and the Nordic countries
Germany's BAföG is a useful case: for students in standard higher education it is paid partly as a grant and partly as an interest-free state loan, repaid at face value after studies. Many Muslim students therefore regard it as acceptable. Additional bank loans in Germany, such as the KfW student loan, do carry interest. In Sweden and Norway the state student loan systems charge interest, but generous grant portions reduce the amount you need to borrow.
Malaysia, the Gulf and other Muslim-majority countries
Islamic banking is mainstream in Malaysia, Indonesia, Saudi Arabia, the UAE, Qatar and elsewhere. Public funding bodies and Islamic banks there offer education financing based on ujrah, murabaha or ijara, and governments frequently award scholarships for study abroad. The sections on student loans in Saudi Arabia and other countries describe the national bodies involved.
United States, Canada and Australia
Federal and provincial student loans are interest-bearing. Australia's HECS-HELP loans are indexed to inflation rather than charged a set interest rate; scholars differ on whether indexation counts as riba. A handful of community-based Islamic finance cooperatives in North America offer qard hasan or murabaha for education, usually to members.
Comparing the options
| Option | How the funder is paid | Typical source | Main limitation |
|---|---|---|---|
| Grant or scholarship | Not repaid | State, university, foundation | Competitive or means-tested |
| Qard hasan | Face value only, possible cost-based fee | Mosque, charity, zakat or waqf fund | Small amounts, limited places |
| Murabaha | Fixed mark-up agreed upfront | Islamic bank | Needs an identifiable asset; credit check |
| Ujrah / ijara | Service fee or rent | Public fund, Islamic bank | Available mainly in Islamic finance markets |
| Interest-free state or honour loan | Face value | Association, foundation, some governments | Selection, sometimes a guarantor |
Illustrative example: a laptop financed by murabaha
Illustrative example with hypothetical figures. A student needs a €1,200 laptop. An Islamic financier buys it and sells it to her for €1,320, a disclosed mark-up of €120, payable over 12 months: €110 per month (12 × 110 = 1,320). If she pays one month late, the price does not rise; a late payment charge, if any, goes to charity under the contract. The equivalent conventional loan would show an APR, but in this structure the whole cost is visible from the start. Always ask for the total amount payable and compare it with other options.
How to apply and what you will be asked for
- Work out what you need and for what: tuition, a deposit, equipment, living costs. In halal student finance, asset-based products suit equipment better than living costs.
- Apply first for every grant and scholarship you are eligible for, including Islamic bodies such as the scholarship programme of the Islamic Development Bank where relevant.
- Ask local mosques, Islamic student societies and Muslim charities whether they run a qard hasan or hardship fund.
- If you approach an Islamic bank, ask for the contract, the Sharia board's approval and a breakdown of all fees.
- Prepare proof of enrolment, ID, a budget, bank statements and, where requested, a guarantor's details.
Students who have no family member able to sign as guarantor can combine these routes with the solutions described for the student loan without a parental guarantor, choosing the interest-free ones.
Pitfalls and false halal labels
- A product described as "interest-free" may still charge fees that rise with time; read the contract, not the advert.
- Be cautious with social-media lenders claiming to be Islamic: fraudsters exploit religious trust to collect upfront fees.
- Check whether compulsory insurance is conventional; some borrowers prefer a takaful policy where available.
- Do not refuse a grant or a means-tested bursary out of caution: non-repayable aid raises no riba issue.
- Remember that late payment on any contract damages your credit record, Islamic or not.
Building a realistic halal funding plan
Few students can cover an entire degree with a single halal student finance product. The most robust plans combine grants and scholarships, a qard hasan for a specific gap, part-time or work-study income, and family support recorded in writing. Start by checking student scholarships that match your profile, then fill what remains with the least costly compliant option. Planning early matters, because community funds and bursaries often have fixed application windows at the start of the academic year.
Zakat and waqf as a source of support
Students with limited means may be eligible to receive zakat, since many zakat committees consider the needy student pursuing beneficial knowledge a legitimate recipient. Waqf endowments, some of them centuries old and others created recently by universities or diaspora communities, fund scholarships and interest-free loans. These funds rarely advertise widely: ask the Islamic society at your university, your local mosque committee and national Muslim relief organisations what they run and when applications open.
Keeping records
Whatever you combine, keep each agreement in writing, note repayment dates and set aside money for them once you graduate. A benevolent lender who is repaid on time can lend to the next student; that is part of the purpose of qard hasan.
Frequently asked questions
Are government student loans halal?
Most government student loans charge interest, which most scholars consider riba, even when repayments depend on income. Some schemes use alternatives: Malaysia's PTPTN uses a service fee, and Australia's HECS-HELP is indexed to inflation, which scholars assess differently. The UK has promised a takaful-based Alternative Student Finance product; check its current status with Student Finance England.
What is a qard hasan student loan?
A qard hasan is a benevolent loan repaid at exactly the amount borrowed. The lender takes no profit, though a small fee covering real administrative costs is usually accepted. Mosques, Muslim charities, zakat and waqf funds and some foundations offer qard hasan to students, typically for limited amounts and with a selection process.
Can I use murabaha to pay tuition fees?
Murabaha requires the financier to buy something and resell it at a disclosed mark-up, so it fits equipment better than tuition. Some providers structure tuition through a service-based contract instead. Ask the provider exactly what is being bought or leased, request the Sharia board's approval, and compare the total payable with interest-free alternatives.
Is an interest-free honour loan acceptable for Muslim students?
An honour loan repaid at face value, without interest, is generally compatible with Islamic principles, which is why many Muslim students in France and Belgium use them. Check that no interest-like charges or conventional insurance with problematic features are attached. If unsure, show the contract to a scholar before signing.
How can I avoid scams offering Islamic student loans?
Deal only with registered banks, known charities or official public bodies. Be suspicious of offers made through social media or messaging apps, requests for upfront fees, and pressure to decide quickly. A genuine provider will give you a written contract, a Sharia approval certificate and a clear total cost before any money changes hands.